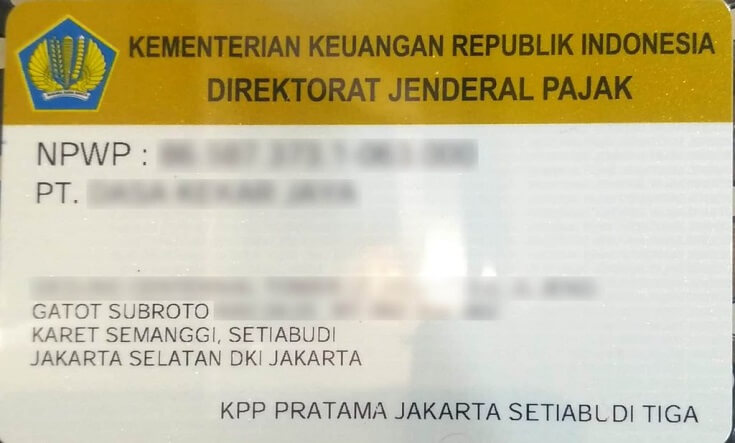
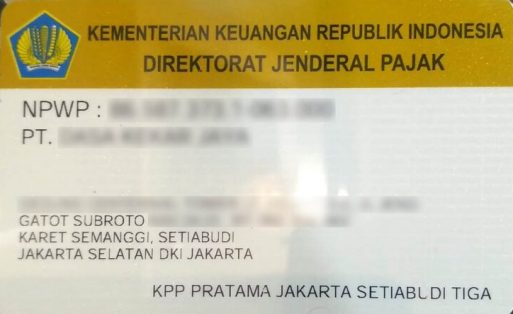
NPWP stands for Nomor Pokok Wajib Pajak, Indonesia’s taxpayer identification number. The Directorate General of Taxes (DJP) uses it to identify individual and corporate taxpayers. An Indonesian company has its own NPWP, separate from its founders’ personal numbers and its NIB business identifier issued through OSS.
Key Takeaways
- NPWP means Taxpayer Identification Number. It identifies the taxpayer for Indonesian tax administration, rather than granting permission to operate a business.
- Corporate taxpayers use a 16-digit NPWP under the system introduced by DJP. A foreign-owned PT PMA has a corporate NPWP distinct from its shareholders’ identifiers.
- Article 40 of Minister of Finance Regulation No. 81 of 2024 requires qualifying corporate taxpayers to register within one month after establishment or domicile in Indonesia.
- NIB is the business identification number administered through OSS. NIK is the population identification number used as NPWP for qualifying resident individuals.
NPWP Identifies the Taxpayer, Not the Business Activity
DJP defines NPWP as the number used to identify taxpayers when exercising their tax rights and meeting their obligations. Its purpose is tax administration.
An individual can hold an NPWP, and a limited liability company can hold another. The numbers identify different taxpayers even when the individual owns all or part of the business.
Consider a foreign shareholder who establishes an Indonesian PT PMA. The company needs its own tax identity. The shareholder’s overseas tax identification number cannot replace the Indonesian company’s NPWP.
Our guide to the PT PMA company structure explains the legal entity behind that distinction. This article concentrates on taxpayer identity and the numbers a company should reconcile.
Compare NPWP, NIB, NIK, AHU and NITKU
Indonesia uses several identification systems during incorporation and ongoing compliance. Each number answers a different question about the company, an individual, or a business location.
| Identifier | Purpose | Responsible System | What It Does Not Establish |
|---|---|---|---|
| NPWP | Identifies a taxpayer for tax administration | DJP and Coretax | Company incorporation or permission to operate |
| NIB | Identifies a business operator and forms part of business licensing | Online Single Submission (OSS) | That every tax obligation or sector approval has been completed |
| NIK | Identifies a person in Indonesia’s population administration and serves as NPWP where the individual meets the relevant requirements | Population administration and DJP | The tax identity of a company owned or managed by that individual |
| AHU company record | Records the legal entity and its formal company documents | Ministry of Law and AHU | Completion of tax or operating licence requirements |
| NITKU | Identifies a taxpayer’s place of business under its central tax identity | DJP and Coretax | A second, independent corporate taxpayer |
Government Regulation No. 28 of 2025 governs Indonesia’s risk-based business licensing framework. Our NIB and OSS guide explains when additional licensing instruments may be required.
The company’s legal record comes through a different authority. Read our explanation of AHU in Indonesia for the corporate record and public company checks.
Corporate NPWP Uses the 16-Digit Format
DJP introduced the 16-digit tax identification format for corporate taxpayers, nonresident individual taxpayers and government institutions. The conversion differs from NIK-based identification for resident individuals.
For an existing corporate taxpayer with a 15-digit NPWP, the standard conversion adds a leading zero. Newly registered corporate taxpayers receive a 16-digit identifier, according to DJP’s Coretax registration guidance.
Do not remove zeros or modify the number for convenience. Check the company’s official taxpayer profile before putting its NPWP on invoices, tax records, or documents requested by another institution.
Taxpayers with multiple business locations should also distinguish NPWP from NITKU, the Nomor Identitas Tempat Kegiatan Usaha. DJP uses the location identifier within a centralized taxpayer structure.
A branch address therefore does not automatically require a separate corporate NPWP. The company’s actual legal structure and its registered business locations determine what must be recorded.
Notes from InvestinAsia Consultants
Create a short identifier register for each Indonesian entity. Record the exact corporate name, AHU decision, 16-digit NPWP, NIB, and relevant NITKU entries. When two systems display different information, compare the underlying record dates before changing a number in the accounting software.
Confirm the Company NPWP After PT PMA Incorporation
A foreign-owned Indonesian PT normally needs corporate tax registration once it is established and meets the applicable taxpayer requirements. Incorporation and tax registration can involve connected government systems.
Article 40 of Minister of Finance Regulation No. 81 of 2024 sets a one-month registration requirement for qualifying corporate taxpayers after establishment or domicile in Indonesia. The regulation has been amended, most recently through PMK No. 1 of 2026.
DJP’s Coretax guidance describes registration channels that include the taxpayer portal, AHU for legal entities, and OSS for business operators. A company should first check whether registration already occurred through that integration.
For company formation, our deed of establishment guide explains what the notary creates. The subsequent ministerial approval decision establishes the conventional PT’s legal-entity status.
Once the legal entity exists, the finance team can verify the taxpayer record. The company’s deed, ministerial approval and tax information should identify the same legal entity.
Check Whether the Tax Number Already Exists
Ask the authorized director or tax representative to inspect the company’s official DJP or Coretax record. Compare its name, address, taxpayer category and 16-digit NPWP with the incorporation documents.
If the data is already correct, avoid submitting a duplicate registration. DJP states that existing taxpayers migrated into Coretax do not need to register again merely because the system changed.
Resolve Missing or Inconsistent Tax Data
If a valid company NPWP is not available, use the current DJP registration route and supporting corporate documents. DJP’s Coretax instructions identify the taxpayer category and documents needed for registration.
Where a record exists but differs from the deed or latest approval, investigate the mismatch with the authorized user. Determine whether the company needs a data update rather than a fresh NPWP.
Set Up Authorized Coretax Access
Obtaining an NPWP and assigning access to a tax preparer are separate tasks. Confirm the company’s responsible person, their digital account rights, and the authority to sign submissions.
Keep credentials under the company’s control. An external accountant may prepare filings, but the director should know which representative can submit documents on behalf of the taxpayer.
Personal NPWP Rules Are Different for Foreign Individuals
A foreign investor’s personal tax position depends on that individual’s circumstances. Owning shares in an Indonesian company does not mean the investor may use the company’s NPWP for personal tax matters.
DJP explains that qualifying resident individuals use their 16-digit NIK as their NPWP. Nonresident individuals who require an NPWP are subject to a different 16-digit registration format.
An overseas shareholder may also need digital access to Coretax in a representative capacity. DJP’s Coretaxpedia explains an account-access route for foreign tax subjects using passport and contact details.
Access to the platform should not be confused with a finding that the person has become an Indonesian resident taxpayer. Tax residency and any personal registration obligation require a separate assessment.
| Scenario | Identifier to Examine | Practical Action |
|---|---|---|
| Indonesian PT PMA reporting corporate tax | Company NPWP | Match the taxpayer profile with corporate records |
| Indonesian resident director or employee | Personal NIK and its NPWP activation where applicable | Confirm personal taxpayer and Coretax status |
| Nonresident foreign shareholder | Personal tax identification or digital access only where required | Assess income, residency and representative role separately |
| Multiple Indonesian locations of one corporate taxpayer | Central NPWP with relevant NITKU information | Reconcile locations with the corporate taxpayer profile |
Do not ask a foreign investor to register as an individual taxpayer merely to make a company’s portal account work. First identify whether they need personal tax registration or a permitted representative-access route.
An NPWP Does Not Automatically Give the Company VAT Status
NPWP identifies the taxpayer. VAT taxpayer status, called Pengusaha Kena Pajak or PKP, involves a separate confirmation or registration process under the applicable VAT rules.
Likewise, an NIB establishes a business identification and licensing position through OSS. It does not show whether the company has completed all corporate tax filings.
A foreign founder receiving a package of incorporation documents should therefore ask for separate evidence of corporate approval, tax identification, NIB and any required VAT status.
For the obligations that may follow registration, our PT PMA corporate tax guide covers tax types and reporting responsibilities. The rules for individual transactions still need a period-specific assessment.
Notes from InvestinAsia Consultants
Before the first invoice or tax filing, compare the company’s name and NPWP across the approved corporate documents, Coretax profile and accounting master data. Keep the confirmation alongside the appointed tax signer’s authority. This catches identity mismatches without treating an NIB or a screenshot of a draft account as proof of tax registration.
Check These Records Before the First Tax Filing
A company can have several registrations and still be missing the information its finance team needs. Review the records together before delegating tax submissions.
- Confirm the entity. Keep the executed deed, ministerial approval and latest recorded amendment relevant to the company.
- Check the corporate NPWP. Verify the 16-digit number, legal name, taxpayer profile and business address through the official tax channel.
- Review the NIB separately. Match the OSS operator and registered activities with the company’s actual business.
- Record operating locations. Check NITKU information where the taxpayer maintains additional places of business.
- Determine VAT status. Verify whether PKP registration applies and whether it has been completed.
- Assign filing responsibilities. Confirm Coretax access, authorized signatories, bookkeeping ownership and the applicable reporting calendar.
- Keep evidence together. Archive official registrations, corrections, notices, payment identifiers and filing acknowledgements.
For a company preparing its first tax reporting cycle, an accurate NPWP is the starting point for connecting the legal entity to its tax filings. It does not determine which taxes are payable by itself.
Choose the Right Tax Support After Registration
If your Indonesian company has an NPWP but no established accounting process, start by confirming the current taxpayer profile and the filings that apply to its transactions.
Our business licensing guide covers permissions outside tax administration. Keep those reviews separate from the finance team’s tax compliance work.
For bookkeeping, financial statements and recurring filings, review InvestinAsia Accounting and Tax Reporting Service in Indonesia. The service page describes available accounting and tax reporting scopes; confirm the specific tax registration and compliance work in the engagement.
Need to Align Your NPWP and Accounting Records?
Review the tax reporting scope for your Indonesian company before its first filing.
- Directorate General of Taxes. (n.d.). Wajib Pajak dan NPWP. Retrieved from
https://pajak.go.id/id/wajib-pajak-dan-npwp - Ministry of Finance of the Republic of Indonesia. (2024). Minister of Finance Regulation No. 81 of 2024 on Core Tax Administration, as amended. Retrieved from
https://jdih.kemenkeu.go.id/dok/pmk-81-tahun-2024/overview - Ministry of Finance of the Republic of Indonesia. (2026). Minister of Finance Regulation No. 1 of 2026, Fourth Amendment to Regulation No. 81 of 2024. Retrieved from
https://jdih.kemenkeu.go.id/dok/pmk-1-tahun-2026 - Directorate General of Taxes. (2024, July 1). Peluncuran Layanan Perpajakan Berbasis NIK sebagai NPWP, NPWP 16 Digit, dan NITKU. Retrieved from
https://www.pajak.go.id/index.php/id/siaran-pers/peluncuran-layanan-perpajakan-berbasis-nik-sebagai-npwp-npwp-16-digit-dan-nitku - Directorate General of Taxes. (n.d.). Coretax Registration. Retrieved from
https://pajak.go.id/id/reformdjp/coretax-registrasi - Directorate General of Taxes. (n.d.). Coretax FAQ on Registration and Taxpayer Access. Retrieved from
https://pajak.go.id/reformdjp/faq/ - Directorate General of Taxes. (2025). Akses Coretax DJP bagi subjek pajak luar negeri. Coretaxpedia, updated 27 November 2025. Retrieved from
https://www.pajak.go.id/coretaxpedia/akses-coretax-djp-bagi-subjek-pajak-luar-negeri - Republic of Indonesia. (2025). Government Regulation No. 28 of 2025 on Risk-Based Business Licensing. Retrieved from
https://jdih.kemenkeu.go.id/dok/pp-28-tahun-2025/overview